The events leading up to 2022 are forcing the banking system to evolve and not just keep up with the times, but even a little ahead. Naturally, the 21-year pandemic has had a huge impact, which has not only altered banking realities, but has also changed the vectors of development. The development of the banking business directly depends on the emergence of new innovative technologies in the banking sector, while the development and promotion of the said technologies are conditioned by the needs of the reproduction process and the type of the economic system.
There are three main catalysts for banking innovation in the banking business:
- globalisation of global financial and banking markets;
- increasing competition among banking and non-banking sectors of the economy;
- the global financial crisis.
Here are eight key trends in banking in 2022.
Special Demand For Super-Apps
Banks are actively discussing building superapps, the demand for which is growing at an unprecedented rate. Superapps combine many valuable customer functions into a single interface. Banking apps have a complex structure, but the daily attention of the customer is drawn to a few basic functions: checking balances, paying bills, viewing transactions, and simple transfers between accounts. For this reason, mobile banking is only 4-5 APIs away from being integrated into any other platform.
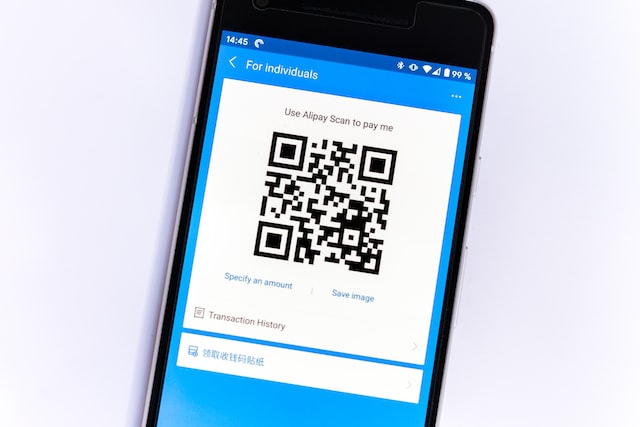
At the same time, the list of true super apps is still short: it includes, for example, AliPay, Amazon, PayTM (India), Kakao (South Korea) and others. This year, banks have a tough choice to make: whether to fight to promote their own superapp, build partnerships with others, or stay out of the race.
“Green” Is the Hit of the Season
The rapid evolution of the ESG agenda is forcing banks to urgently establish mechanisms to obtain data and measure their own progress towards the Sustainable Development Goals (SDGs). Bank of America estimates that about $150 trillion in total investment is needed to achieve carbon neutrality. Financial institutions will have to take on a new role as protectors of the planet, at considerable cost. But this investment can pay off in the long term in terms of employee motivation, customer confidence, investor interest and regulatory loyalty.
Heading For Innovation
Traditional banks are losing weight in the economy. At the same time, fintech companies and alternative financial players continue to win back consumers and increase their capitalisation. Digitalisation has become a necessity, but digitising processes alone cannot differentiate bank services and support revenue growth. Because of this, banks will have to creatively rethink which operations and offerings innovation will create the most value for customers. Banks are not only rethinking traditional views of services and customer segments, but also opening up new collaborative business models. Increasingly, they see their own technology as a new product and potentially a new source of revenue.
Streamlining of Bank Charges
Banks’ policies regarding charging fees have changed many times. In competition with the widespread offer of free service, banks have been forced to move from relatively transparent fees to hiding fees – through late payment penalties, overdraft charges and so on. By 2022, increasing competition and digital transparency are pushing banks and fintech companies to rethink their approach: all fees should once again be simple and straightforward. In contrast, new customer offerings will increasingly focus on helping customers optimise costs and make financial decisions that benefit them.
Direct Contact With the Customer
From 2018 to 2020, customer confidence in banks has declined, particularly in terms of lending. One reason is that banks have stopped talking to the customer face-to-face. In 2022, banks are looking for ways to return to substantive conversations. Their challenge is to regain empathy in communication with the customer and to understand financial and emotional circumstances more deeply in order to restore loyalty.
Digital Currencies Are Maturing
By the end of 2021, 78 countries around the world are researching digital currencies: six of them have already launched their own digital currencies and at least 17 are in the process of piloting them. For example, Switzerland and Singapore are already piloting digital currencies for cross-border payments, and China’s retail digital currency project has already reached more than 140 million users with more than $9.5 billion in transactions. The further focus of digital currencies development is to identify specific application scenarios where they can have maximum economic impact.
Minimising Human Intervention via Smart Transactions
Banks have reached a point where human involvement in transactions is unnecessary. For example, voice and text analysis technologies are already helping to get the job done many times faster and more accurately. Sixty to 70% of the operational tasks involved in lending can already be reduced by converting income and other documents into a standardised form.
Universal Payments
According to global analysts, the next payment revolution will come from the development of open networks. Consumers already take it for granted that they can pay and receive money anywhere and anytime. The industry is already on the verge of allowing them to pay any way they want. Regulators are pushing the market to remove restrictions on consumer-accessible payment methods, such as in China and India, and to use uniform standards. The development of open payment infrastructures at the country or even regional level, as in Europe, will be a catalyst for change and provide a better link between investment and innovation.