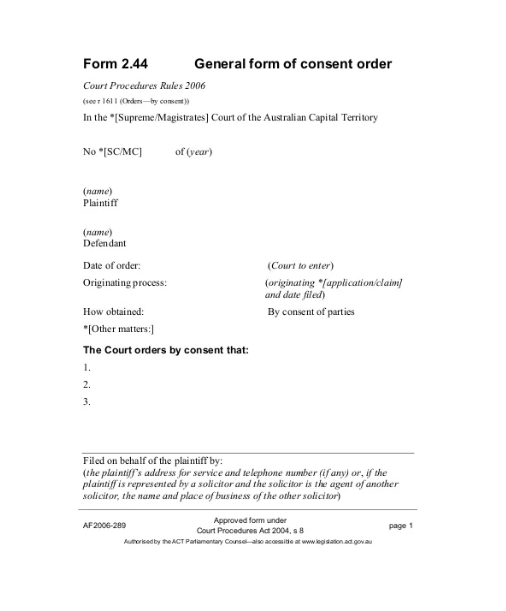
In the realm of banking, consent orders (COs) play a crucial role in ensuring regulatory compliance and addressing deficiencies. But what exactly is a CO?
This article delves into the intricacies of COs in banking, shedding light on their nature, purpose, and process of issuance.
Gain a comprehensive understanding of how these agreements shape the landscape of the industry and drive institutions toward rectifying shortcomings.
What is a Consent Order in Banking?
After the 2008 financial crisis, regulatory authorities worldwide intensified their efforts to ensure financial system stability and consumer protection. One of the most important tools used by regulatory bodies to ensure banks’ compliance with regulatory requirements and address deficiencies is a cCO.
A CO is a legally binding agreement between a financial institution and a regulatory body that requires the institution to take specific corrective actions to address identified deficiencies.
The Nature of Consent Orders
A CO is an agreement reached between a regulatory body, such as a central bank or financial supervisory authority, and a financial institution. It is applied in cases where the regulatory body identifies significant violations of the laws, regulations, or best practices within the organization.
Instead of resorting to more punitive measures such as enforcement actions or fines, regulatory authorities often prefer to use COs to encourage cooperation and remediation by the institution. By entering into an agreement, the financial institution acknowledges its deficiencies and commits to taking necessary measures for their prompt resolution.
Purpose and Objectives
The main purpose of a CO is to prompt financial institutions to address violations and promptly implement corrective actions. The agreement specifies specific corrective measures that the bank must undertake to achieve compliance with relevant laws and regulations.
The objectives of COs include:
| Purpose and Objectives | Description |
|---|---|
| Ensuring Consumer Protection | Addressing unfair or deceptive practices to safeguard consumer interests. |
| Enhancing Financial Stability | Rectifying practices that could jeopardize the stability of the financial system. |
| Improving Risk Management and Governance | Implementing measures to strengthen risk management and governance structures. |
| Preventing Money Laundering and Terrorism Financing | Addressing deficiencies in anti-money laundering and counter-terrorism financing efforts. |
Regulatory bodies can issue consent orders to address deficiencies in anti-money laundering and counter-terrorism financing efforts, aimed at preventing illegal activities in the sector.
Process of Issuing Consent Orders
The process of issuing COs involves several key stages followed by regulatory bodies when identifying compliance issues in a financial organization and reaching an agreement for their resolution.
Typically, the process includes the following stages:
- Regulatory examination or investigation: The process begins with an examination or investigation conducted by the respective supervisory or regulatory institution. This stage involves assessing the bank’s operations, risk management practices, governance structure, as well as compliance with applicable laws and regulatory requirements;
- Identification of compliance-related issues: Based on the examination or investigation results, the regulatory body identifies specific problems or deficiencies in the operations of the financial institution. These issues may pertain to consumer protection, risk management, anti-money laundering procedures, capital requirements, or any other regulatory matters;
- Interaction and Communication: Once regulatory authorities identify compliance issues, they communicate their findings to the bank’s board of directors and senior management. The bank is informed about the identified deficiencies, and negotiations for their resolution may commence;
- Agreement on Corrective Actions: Following the notification of identified deficiencies, the regulatory body and the bank enter into negotiations to determine the necessary corrective actions. The goal is to establish a set of specific measures and actions that the bank must undertake to effectively address the deficiencies;
- Preparation of the Draft CO: Based on the negotiations, the regulatory body prepares a draft CO, which is an official legal document outlining the terms of the agreement. It contains detailed information about the identified deficiencies, required corrective actions, timelines for implementation, and other important provisions;
- Review and Approval: The draft CO is reviewed by the legal department of the regulatory body as well as legal representatives of the bank to ensure accuracy and completeness. After necessary changes are made, the final version of the CO is approved by both parties;
- Signing the CO: Upon approval, representatives of the regulatory body and the bank officially sign the CO, indicating their agreement with its terms. By signing the CO, the bank voluntarily acknowledges the identified deficiencies and commits to addressing them in accordance with the agreed-upon actions;
- Implementation and Compliance Oversight: After signing the CO, the bank’s board of directors and management become responsible for successfully executing the corrective actions. The bank appoints responsible individuals or teams to monitor the progress of each action and regularly provides reports to the regulator on the work done;
- Monitoring and Subsequent Actions: The regulatory agency monitors the bank’s progress in implementing the corrective measures outlined in the CO. Regular follow-up meetings or reports may be scheduled to track the bank’s compliance with requirements and address any issues that arise during the process;
- Conclusion and Termination: Once the bank satisfactorily rectifies all identified deficiencies and fulfills the requirements of the CO, the regulatory body confirms the completion of the agreement. Subsequently, the CO’s effectiveness ceases, signifying the successful resolution of compliance-related matters.
It is important to note that the process of issuing COs may vary depending on the specific regulatory body, the severity of identified deficiencies, and the individual circumstances of the financial organization. The aim of this process is to foster cooperation between the regulatory body and the bank, leading to improved compliance with regulatory requirements and strengthened banking practices.
Impact on Banking Operations
Issuing a CO can have a significant impact on the operations of a financial institution, ranging from its day-to-day activities to long-term strategic planning.
The consequences of a CO decision are multifaceted and can affect various aspects of a bank’s functioning.
Here are some key implications for banking operations:
| Impact on Banking Operations | Description |
|---|---|
| Financial Costs and Resource Allocation | Significant financial investments and allocation of resources to implement corrective actions. |
| Operational Changes and Process Reforms | Modification of policies, procedures, and risk management practices to align with regulatory requirements. |
| Restrictions on Business Activities | Potential limitations on certain business transactions or expansion plans until compliance issues are resolved. |
| Reputation and Customer Trust | Negative implications on the bank’s reputation, potentially leading to decreased customer trust and investor confidence. |
| Increased Regulatory Scrutiny | Heightened regulatory examinations and reviews during the CO period to monitor compliance efforts. |
| Impact on Market Positioning | Possible loss of market share and competitive advantage due to negative publicity, leading to challenges in attracting new business. |
| Board and Management Accountability | Increased responsibility and scrutiny on the board and senior management for overseeing corrective actions and compliance. |
| Time and Effort Investment | Substantial time and effort are required to address compliance issues, potentially impacting other strategic initiatives. |
| Long-Term Organizational Impact | Potential shifts in risk appetite and organizational culture, affecting the bank’s long-term growth and strategic decision-making. |
The impact of a CO on banking operations can be far-reaching and complex. While this process aims to increase the level of regulatory compliance and enhance the overall integrity of the financial system, it is also accompanied by challenges and disruptions for the affected institution.
Successfully navigating the period of a CO requires an active and transparent approach to compliance, as well as a commitment to addressing core issues comprehensively.
Role in Enhancing Regulatory Compliance
The issuance and enforcement of COs play a crucial role in improving compliance with regulatory requirements in the industry.
By holding financial organizations accountable for their actions and requiring them to take specific measures to rectify the situation, COs contribute to fostering a culture of regulatory compliance and responsible practices.
Below are key roles that COs play in enhancing regulatory compliance:
| User Role in Enhancing Regulatory Compliance | Description |
|---|---|
| Fostering a Culture of Compliance | Encouraging bank employees to prioritize compliance and ethics, fostering a culture that values regulatory adherence. |
| Empowering Staff with Training | Providing comprehensive training programs to educate employees about relevant laws, regulations, and best practices. |
| Implementing Internal Controls and Monitoring | Establishing robust internal controls and monitoring procedures to prevent and address compliance deficiencies. |
| Encouraging Whistleblowing and Reporting Mechanisms | Establishing confidential reporting channels for employees to report potential compliance violations. |
| Promoting Customer Awareness | Informing customers about their rights, and responsibilities, and transparently disclosing terms of financial products. |
| Customer Due Diligence (CDD) and Know Your Customer (KYC) | Ensuring thorough CDD and KYC practices to prevent money laundering and fraud. |
| Complying with Data Privacy and Security Regulations | Educating users about data protection measures and adhering to data privacy and security regulations. |
| Embracing Technological Solutions | Participating in the successful adoption and usage of technological solutions to streamline compliance processes. |
Enhancing compliance with regulatory requirements in the industry necessitates collective efforts from all stakeholders, with users, including employees and customers, playing a pivotal role.
Cultivating a culture of adherence, providing staff training, increasing customer awareness, and leveraging technology are key elements in strengthening commitment to regulatory compliance.
Recognizing the significance of user involvement in the compliance equation enables banks to build a resilient and trustworthy financial ecosystem that benefits all stakeholders.
Conclusions
Consent orders in the industry serve as important regulatory instruments, ensuring financial institutions’ compliance with laws and regulations. The mandatory nature of these agreements compels banks to promptly address identified deficiencies, promoting consumer protection, financial stability, and effective risk management.
While COs may present certain challenges for banks, they ultimately contribute to fostering a culture of compliance and accountability within the sector, reinforcing the integrity and resilience of the overall financial system.